
Embedded finance is rapidly reshaping the financial services industry, introducing a paradigm where non-financial companies seamlessly integrate financial services into their products and services. This approach is transforming how businesses interact with consumers by offering a more streamlined and integrated user experience.
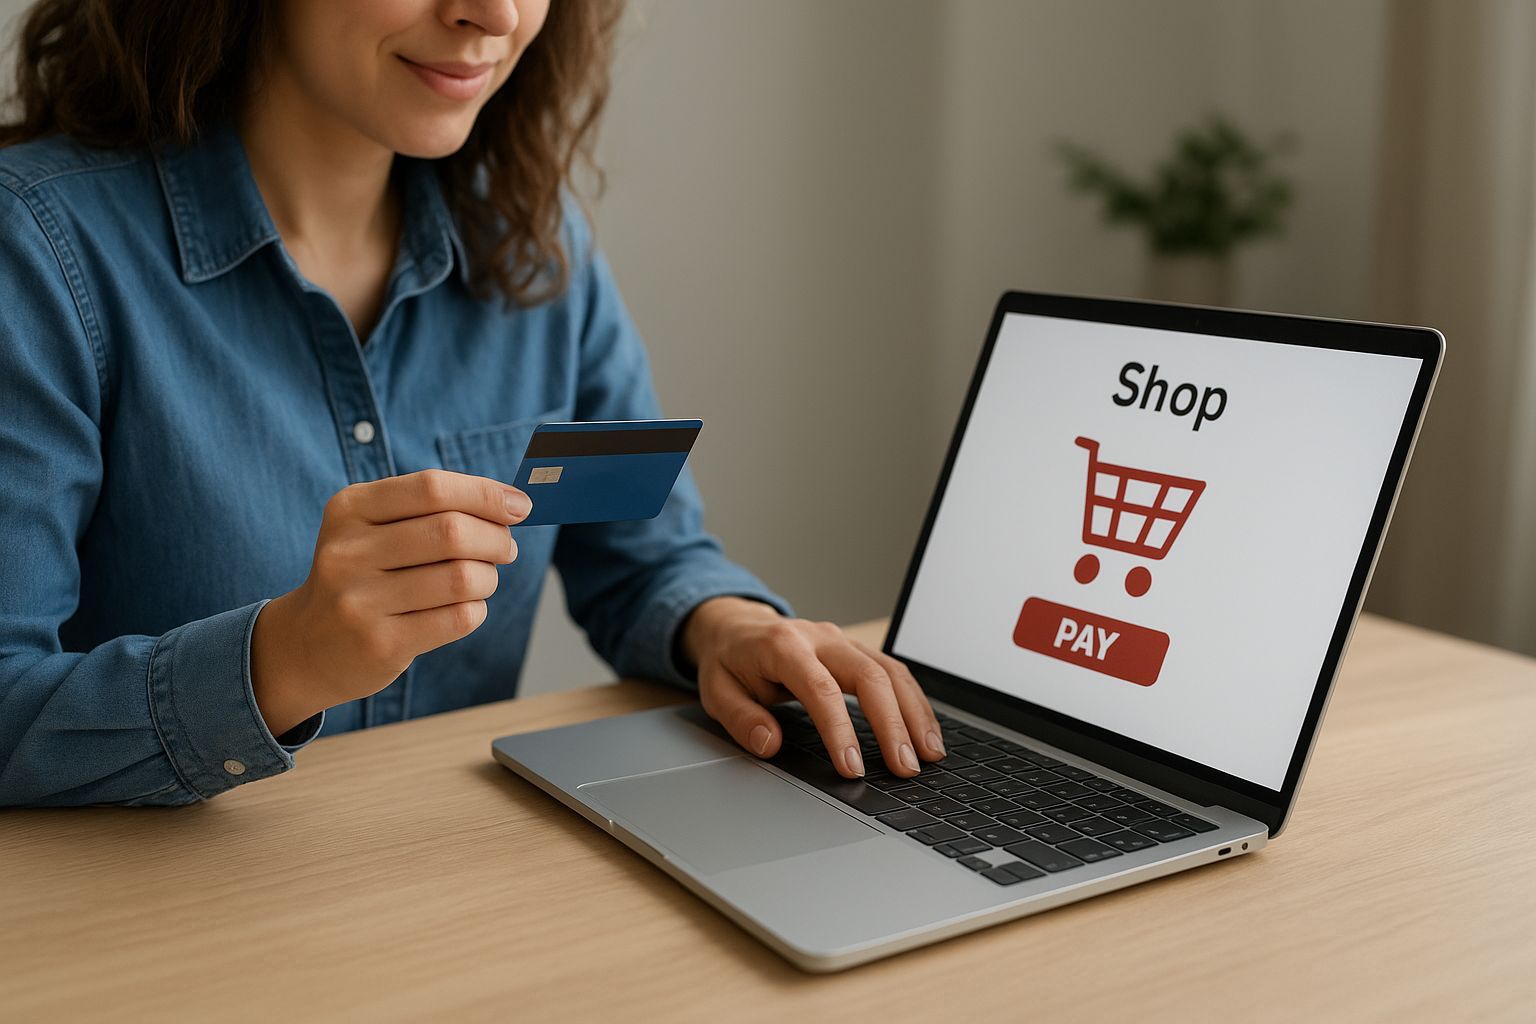
A rising trend within embedded finance is the incorporation of banking services directly into platforms that were traditionally not associated with financial services. For instance, e-commerce platforms are now offering credit lines and payment solutions directly at the point of sale. This integration allows consumers to stay within the e-commerce environment, enhancing convenience and increasing purchase completion rates.
The financial benefits for businesses adopting embedded finance are significant. Companies can tap into new revenue streams by monetizing the financial services layered into their existing offerings. Additionally, it helps businesses gather more comprehensive consumer data, enabling tailored marketing and enhanced customer engagement strategies. For instance, ride-sharing companies offering insurance or lending services capitalize on their already vast user data to deliver personalized offerings.
From a regulatory perspective, embedded finance poses new challenges. Companies must navigate complex regulatory environments to ensure compliance with financial laws and regulations such as anti-money laundering (AML), know-your-customer (KYC), and data protection standards. As the line between traditional finance and technology blurs, the need for clear regulatory guidance grows. Jurisdictions like the European Union are actively developing frameworks to regulate non-traditional service providers embedding financial products. For example, the upcoming EU Payment Services Directive aims to broaden the horizon for open banking and embedded finance.
Security concerns also come to the forefront with the rise of embedded finance. The integration of financial services into various platforms increases the risk of data breaches and fraud. As such, businesses must enhance their cybersecurity measures and ensure robust encryption and authentication mechanisms are in place. Fintech companies are investing rapidly in AI-driven security systems that can detect and mitigate fraud in real time, making embedded finance both safer and more reliable.
Examples of successful implementation abound. Consider the partnership between Shopify and Stripe, where Shopify sellers can offer loans to businesses using embedded finance capabilities. Similarly, companies like Uber offer financial services like vehicle financing, paid directly from the driver’s earnings, illustrating operational efficiencies achieved through embedded offerings.
As we look to the future of financial services, the expansion of embedded finance represents an undeniable shift in the market. As more industries adopt these practices, financial services providers must remain agile, adapting to an ecosystem that prioritizes convenience, efficiency, and consumer-centric solutions.